Nº 02 · 9 Oct 2026
Opening-range breakout: the profit was an impossible fill
- With a next-open fill
- 0.71 / 0.88 / 0.94
- Market
- Nasdaq CFD, 3.7 pt cost
- As published, impossible fill
- 1.66 / 1.76 / 2.35
Give it a fill you could actually get and the edge disappears in every year.
Read the autopsyclaim · method · every number · the raw chart
Source: YouTube Nasdaq day-trading channel
The backtest filled at a price no broker gives you.
Even the random controls passed, because they got the same free fill.
This verdict is about the strategy as published, not about the person who shared it.
The claim
Here’s what the strategy promises, in its own terms.
Buy the break of the opening range on Nasdaq; backtests show profit factor 1.7-2.4 every year.
How we tested it
Same six checks as everything else here: random entries, coin flips, a look-ahead audit, unseen years, double costs and a luck check. How we test →
What we found
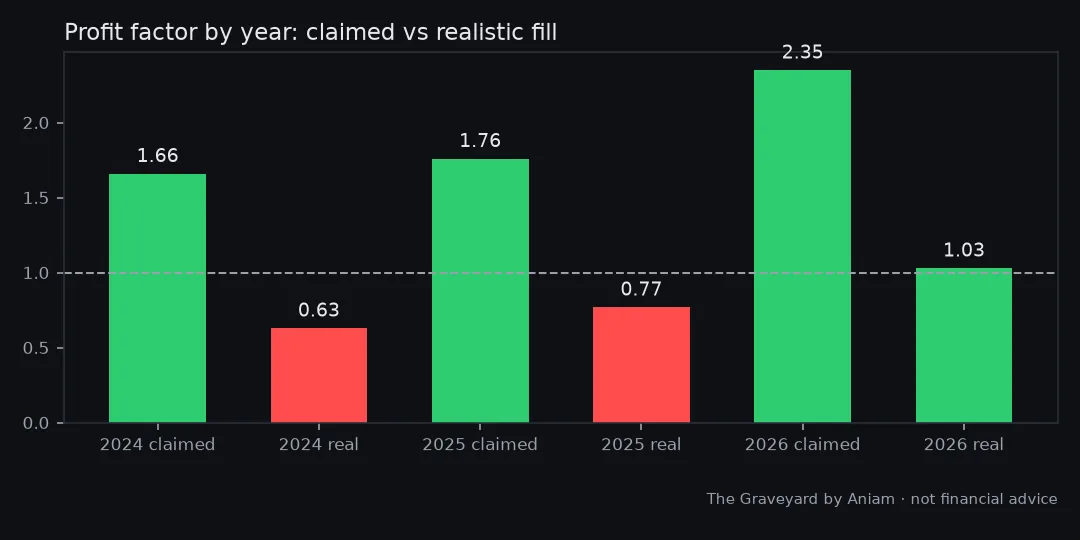
The published backtest fills you at the range edge on the bar that already closed past it, which no broker can do. With a limit at the edge (filled only when price comes back) the profit factor fell to 0.63, 0.77 and 1.03 for 2024, 2025 and 2026. With a market order at the next open it was 0.71, 0.88 and 0.94. The coin-flip and random controls had passed too, because they inherited the same free fill.
The numbers
The headline numbers from our test.
| Claimed PF by year | 1.66 / 1.76 / 2.35 |
|---|---|
| Limit fill PF by year | 0.63 / 0.77 / 1.03 |
| Next open fill PF by year | 0.71 / 0.88 / 0.94 |
| Market | Nasdaq CFD, 3.7 pt cost |
- Profit factor: money won divided by money lost. Below 1.0 loses money. Around 1.0 is break-even.
- R-multiple: profit or loss measured in units of the amount risked per trade. +1R means you made what you risked.
- vs random: how the strategy did against the same trades with random entries.
You’re on the list.
Your first issue arrives with the next weekly send. Until then, the graveyard is open.